
Investors for Paris Compliance has written to the audit committee chairs of 14 major Canadian oil and gas companies warning of “material gaps” in how they disclose decommissioning liabilities, and threatening to withhold votes at this spring’s annual meetings if the 2025 financial statements do not improve.
Letters to 14 audit chairs
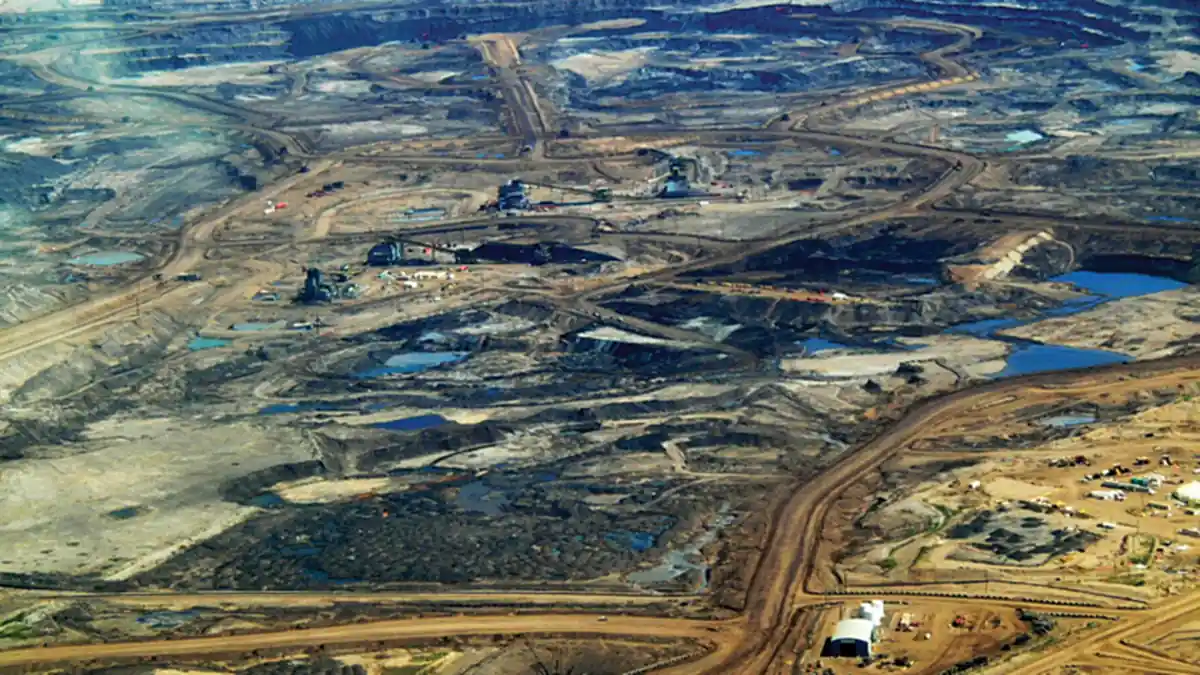
The investor advocacy group says its research found “material gaps” in the companies’ 2024 disclosures around the funds set aside for decommissioning operations — the wells, pipelines and facilities that must eventually be shut down, dismantled and remediated — potentially affecting billions of dollars in shareholder capital.
Executive director Matt Price wrote to the audit committee chairs at 14 major oilpatch companies outlining the concerns and what should be done to address them in the upcoming financial reports. The letters were also copied to the companies’ external auditors.
Price said the audit committees should explain their assumptions around costs, commodity prices, asset lives and other matters that determine how large the cleanup obligation appears on the balance sheet. He also said the firms should disclose how their financial position may change under a scenario with a faster transition away from fossil fuels, and that transition risks should be reflected in financial reporting.
Votes on the line
The warning comes with a deadline and a sanction. The group said that if the issues are not adequately addressed in the companies’ 2025 financial statements, it would withhold support for the re-election of audit committee chairs and for the reappointment of external auditors at the companies’ annual meetings this spring.
“Your company operates in a sector with significant risks related to decommissioning liabilities and demand shifts due to the energy transition,” Price wrote. “As your company prepares its 2025 financials, it is critical that appropriate practices in accounting for its decommissioning liabilities are applied, and that the auditor demonstrates robust independent assurance in this regard.”
Why the numbers can swing so widely
Decommissioning liabilities — formally, asset retirement obligations — are estimates, and small changes in the assumptions behind them move the reported figure by billions. A higher discount rate shrinks the present value of cleanup costs decades away; longer assumed asset lives push those costs further into the future; and assumptions about future oil and gas prices affect how long a field is expected to keep producing.
That is why investors say the disclosure matters as much as the number itself. In a report released in November 2025, Investors for Paris Compliance found that Canada’s top 15 oil and gas producers could be underreporting their decommissioning liabilities by billions of dollars. The report identified a $113-billion gap between what appears in the companies’ financial statements and a leaked 2018 Alberta Energy Regulator estimate of total industry liabilities. It cited a widespread failure to disclose cleanup timelines and sensitivity analyses for costs, inflation and discount rates, along with accounting judgments — long remediation timelines, high discount rates and optimistic commodity prices — that minimize the liabilities on paper.
The group also faulted auditors, saying there is no public evidence they have tested the optimistic assumptions underlying the figures.
The escalation that followed
The January letters were explicitly framed as notice. Investors for Paris Compliance later confirmed it sent open letters in January 2026 to the audit chairs of Canada’s largest 14 upstream oil and gas companies, and that it would assess their 2025 financials against the gaps it had identified.
When those statements came out, the group followed through on the threat, announcing votes against the re-election of audit committee chairs and the reappointment of auditors at companies whose reporting had not improved — flagging Suncor Energy and Cenovus Energy, two of the country’s largest producers, in its 2026 annual meeting escalation, and keeping Imperial Oil under close review.
The dispute is ultimately about who pays to clean up the oilpatch. If reported liabilities prove too low, the shortfall risks landing with shareholders, landowners or governments — which is why a technical accounting fight is drawing a political audience.